PayDirectNow: Pros, cons and where to play
Weighing PayDirectNow’s strengths, its weak spots and where players will find it
LONDON LEARNED THIS summer how thin the margins in payments can be. Paystone, the local processor that once talked about becoming the city’s first unicorn, entered creditor protection in June with a $92-million debt load. A judge then rejected its plan to sell itself back to its founders and ordered a court-supervised auction. The founders’ numbered company emerged as the approved buyer anyway, with court approval in late August. However the sale closes, the point stands. Whoever moves the money carries the risk.
While that played out, the rest of the industry kept moving toward the bank account itself. Payments Canada admitted its first five payment service providers as direct members in January, and six more members on October 1. The Real-Time Rail is due to switch on this quarter. Interac’s Konek wallet signed Global Payments on September 29. The place where that shift finished years ago is the cashier of a regulated online casino, where Interac options usually top the list. iGaming Ontario counted 1.2 million active player accounts in August and $9.7 billion in wagers, all from players 19 or older.
One of the companies behind those Interac buttons is PayDirectNow. It is the consumer brand of Toronto’s Paramount Commerce, and one of the five providers Payments Canada admitted in January. It is the subject of this piece. What it does well, where it falls short, and which PayDirect casinos a player can actually use. Please note this article is reader-supported.
What PayDirectNow is
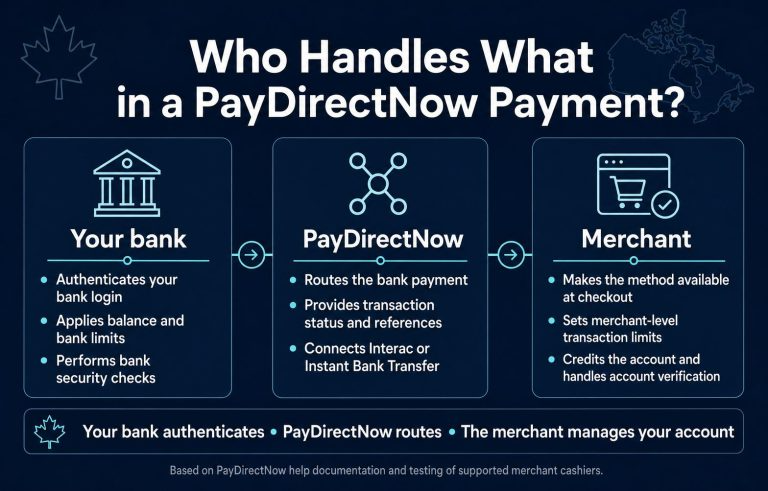
PayDirect is the name at checkout. Paramount Commerce, the company behind it, has been doing pay-by-bank from Toronto since 2003. Back then the alternative was loading an e-wallet and waiting up to two business days for the money to move. By its own count it now serves more than four million active Canadian consumers and has processed over $100 billion. You pay one of two ways. Through Interac, you approve a request in your banking app or send an e-Transfer. Through Instant Bank Transfer, you log in to your bank inside the checkout. Both draw from a chequing or savings balance. Neither touches a card network.
Where to play: PayDirect casinos in Canada
New players anywhere in Canada can deposit with PayDirect at Grand Mondial, a brand registered with iGaming Ontario for Ontario players and licensed separately for the rest of the country. The legal age is 19 in Ontario and 18 or 19 elsewhere, depending on the province. Online gaming is the sector where PayDirect is easiest to find, and this cashier lists it for both deposits and withdrawals, sometimes under an Interac label rather than by brand name.
Grand Mondial is operated in Ontario by Apollo Entertainment Ltd, the Casino Rewards group’s registered entity in the province. Outside Ontario the same brand is managed by Fresh Horizons Limited under a Kahnawà:ke Gaming Commission licence. The Suburban’s guide to PayDirect casino options in Quebec covers that side of the market, including how to check a licence against the Kahnawà:ke directory.
Players are advised to wager responsibly. Resources for help include ConnexOntario or 1-866-531-2600.
How a PayDirectNow payment works
Pick Interac at the cashier and PayDirect asks which bank you use. With Request Money, a request for the exact amount is waiting in your banking app. Approve it and the merchant is told immediately. With Send Money, the screen gives you a recipient and a unique code. You log in to your bank, send an e-Transfer for the amount and paste the code in the message field. The code is valid for two hours. A request you ignore expires after 24 to 48 hours and nothing moves.
Instant Bank Transfer is shorter. You choose your bank, sign in with your usual credentials, pick an account and confirm the amount. Funds show on the merchant’s side within seconds, occasionally a few minutes. The first time through, PayDirect stores a secure token for that account. After that, a deposit or a withdrawal to the same account is one click, with no bank login.
Fees and limits sit with your bank, not with PayDirect. The company charges nothing on the consumer side, though some banks charge a small fee per e-Transfer. PayDirect’s own documentation puts the platform ceiling at $99,999 for an Interac payment and $25,000 for an Interac withdrawal, and up to $100,000 either way for Instant Bank Transfer. Those are maximums the system allows, not amounts you will get. Your bank’s daily e-Transfer limit is the number that matters, and it is usually far lower.

The pros, measured
Speed is the obvious one. A Request Money approval gives the merchant immediate access to the funds. Instant Bank Transfer confirms in seconds. Even the manual Send Money route is usually received within five to ten minutes. The outside case is 30 minutes, when the Interac network runs extra checks.
The second is the return trip. PayDirect handles withdrawals as well as deposits, on the same rail. An Interac withdrawal arrives as an e-Transfer. If your bank has auto-deposit switched on, the money lands the moment the operator approves it. An Instant Bank Transfer withdrawal goes back to the tokenized account in two to five business days. In and out through one provider is a realistic expectation here. Not every pay-by-bank processor can say that. The stored token helps too. After the first Instant Bank Transfer, a deposit or a withdrawal to that account is one click.
The third is the paper trail. Whatever the cashier calls the button, the word PAYDIRECT shows up in your bank statement. The exact line varies by bank, according to the company’s own documentation, but it carries a reference number and usually ETRANSFER or INSTANT BANK TRANSFER beside the name. On a manual e-Transfer the recipient may appear as PayDirect Billing Solutions. Either way, you always know who moved the money. PayDirect also runs its own consumer support by email and live chat, separate from the operator. Its documentation tells users not to take PayDirect problems to Interac, which tells you where responsibility sits.
The fourth is institutional weight. Paramount, registered as Element Financial Technology Inc., sits on the Bank of Canada’s registry of payment service providers under the Retail Payment Activities Act. It reports to FINTRAC as a money services business. Since January it has also been a member of Payments Canada, alongside Wise, KOHO, Float and Brim. That seat is the ticket to joining the Real-Time Rail directly rather than through a bank. The Bank does not endorse the firms on its registry, but registration does mean supervision of how user funds are safeguarded. Twenty-three years in business on top of that is more than most casino payment processors can show. And payments come from a balance, never from a credit line, so a deposit that exceeds what is in the account simply fails.
The cons, measured
The first problem is the name on the button. PayDirect’s Interac product is one of several that operators present under a plain Interac label. Gigadat, Payper and Loonio sit behind similar wording at other cashiers. At PayDirect casinos the brand name may only appear on the next screen. The only sure confirmation is the PAYDIRECT descriptor on your statement, after the fact. The phrase Instant Bank Transfer is generic too. Other processors use it.
The second is finality. An accepted e-Transfer or account-to-account transfer cannot be recalled by the sender, and the Real-Time Rail is designed the same way. Credit cards come with dispute rights. Federal rules cap liability for unauthorized card use at $50, and issuers give you weeks to contest a charge. None of that travels with you here. This is a method for operators you have already checked against the iGaming Ontario regulated market list, not for trying an unfamiliar one.
The third is the Send Money route itself. It depends on you entering the right recipient and the right code within a two-hour window. Get the code wrong and the transfer can sit unmatched. PayDirect’s support can trace it, but that is a conversation you would rather not have. Request Money and Instant Bank Transfer remove that step. Use them where the cashier offers them.
The fourth is that instant describes the deposit, not the payout. The operator still has to approve a withdrawal, and licensed sites run identity checks before the first one. An Interac withdrawal then waits for you to accept it unless auto-deposit is on. An Instant Bank Transfer payout takes two to five business days. None of that is PayDirect’s doing, but a player who assumes symmetry will be disappointed.
The fifth is the limit question. The ceilings above belong to the platform, not to you. Your bank’s e-Transfer limit governs, and most banks set it in the low thousands per day. Raising it means a call to the bank, not a setting inside the cashier. Operators add their own caps, and almost none publish a schedule that separates one Interac processor from another.
The sixth is the flip side of the token. One-click deposits remove the small pause that a bank login used to impose. Players who want that pause should set a deposit limit with the operator before the first transaction.
The seventh is reach. PayDirect works in Canada, in Canadian dollars, for adults with an account at a Canadian bank or credit union. It has no use at a foreign shop. Konek, with Global Payments behind it, is heading for everyday retail. PayDirect’s visible footprint is still mostly the gaming cashier and a scatter of online checkouts.
The verdict
PayDirectNow scores well on speed, on same-rail withdrawals and on the depth of its regulatory file. It scores poorly on recourse, on cashier labelling and on the gap between an instant deposit and a multi-day payout. The one-click token cuts both ways. For a player funding an account at an operator they already trust, using money already in the bank, it is one of the more complete pay-by-bank options around. For anyone who wants chargeback rights, or a method that also works at the grocery store, it is the wrong tool.
If you want to try it, Grand Mondial is one of the PayDirect casinos open to Ontario players, sometimes under an Interac label. Confirm the operator on iGaming Ontario’s list before depositing. Then check your statement for the PAYDIRECT line, so you know exactly who handled the money.
London’s payments story this year was about what happens when a processor’s balance sheet gives way. PayDirect is built on the opposite premise. It extends no credit, touches no card network and moves money only when it is already there. That does not make it right for every player. It does make it easy to judge, and both columns of the ledger are now in front of you.